Company Law

  • Blog - Company Law

    Post-Incorporation Compliances in India after Company Registration
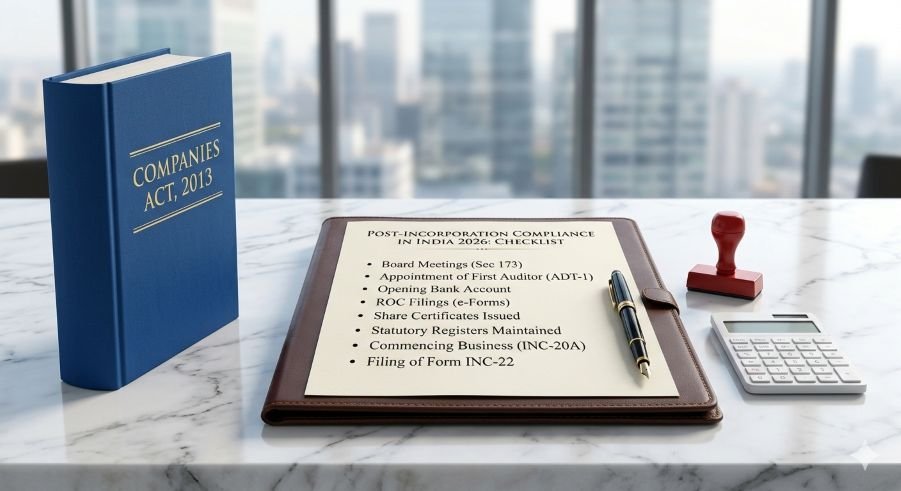
    Post-Incorporation Compliance in India for company

    Post-Incorporation Compliance: The Certificate of Incorporation serves as conclusive evidence of the legal existence of a company under the Companies Act, 2013. However, registration or incorporation alone does not enable a company to commence its business operations. Upon registration, the Company must complete the necessary post-registration formalities and comply with the statutory requirements prescribed under the Companies Act, 2013, and the rules made thereunder.

    These may be broadly categorized as mandatory requirements under applicable laws, including the Companies Act, 2013; and recommended practices that support the effective functioning of the Company’s business operations.
    Mandatory Post-Incorporation Compliance Requirements for Company:After incorporation, a company

    Mandatory Post-Incorporation Compliance Requirements for Company: After incorporation, a company is required to comply with certain legal and statutory requirements, which are as follows:

    Company Post-Incorporation

    (Mandatory Compliance Check List)

    S.NoNature of Compliance/ EventRelevant Act/ Regulation/ StandardDue Date / Timelines
    1Opening of a Current Account with the bank selected in SPICe+ at the time of incorporation or with any other bank of choice, as applicable.Prerequisite for Subsequent Mandatory ComplianceWithout Undue Delay
    2Verification of the Registered Office Address Post-Registration of a CompanyThe Form INC-22 as per Companies Act, 2013 and its related company incorporation rules.
     
    Note: Applicable only if the registered office address was not provided in SPICe+ Part B at the time of incorporation.
    Within 30 days from the date of incorporation
     
    Note: It does not mean one month
     
    3Declaration of commencement of businessThe Form INC- 20A as per Companies Act, 2013 and its related company incorporation rules.
     
    Note-1: Applicable only to companies having share capital.
     
    Note-2: Ensure that the registered office address of the company is updated through Form INC-22 or Form SPICe+ Part B before filing the said Form INC-20A
    Within 180 days from the date of incorporation.
     
    Note: It does not mean six months.
    4First Board meeting Convene the first meeting of the Board of Directors as per Section 173(1) of the Companies Act, 2013, and ICSI Secretarial Standard–1 (SS-1).Within 30 days from the date of incorporation, with at least 7 days’ prior notice.
    5Appointment of first auditorThe Board of Directors must appoint the company’s first auditor under Section 139(6) of the Companies Act, 2013.
     
    Note: Not applicable to Government companies.
    Within 30 days from the date of incorporation 
    6Issue of share certificatesUnder Section 56(4)(a) of the Companies Act, 2013, the company must issue share certificates to the subscribers of Memorandum of Association (MoA), after receiving the subscription money.Within two months from the date of incorporation
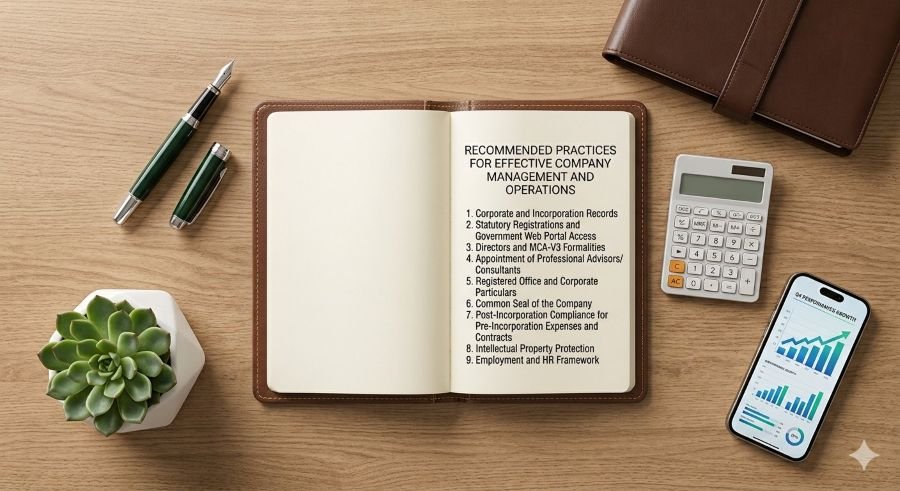
    Post-Incorporation Compliance Recommended Practices for Effective Company Management and Operations

    Post-Incorporation Compliance: Recommended Practices for Effective Company Management and Operations: are suggested measures to help the Company function smoothly and efficiently after incorporation, based on its business, size, operational needs, and applicable laws, and are not mandatory requirements.

    1. Corporate and Incorporation Records: Maintain and organise all key company documents, including the Certificate of Incorporation, Memorandum (MOA), Articles (AOA), approvals, and other legal records. Keep updated copies easily accessible for business, banking, legal, and regulatory needs.
    2. Statutory Registrations and Government Web Portal Access: Maintain the Company’s PAN, TAN, government registrations, and web portal access, including MCA and income-tax portals. Keep access secure, documented, and regularly reviewed.
    3. Directors and MCA-V3 Formalities: Ensure all directors and authorised personnel complete their MCA V3 Web Portal profiles and required formalities. For more detailed information, Please read Director Identification Number (DIN) and DPIN for LLP-2026 and Please click here to create or update your MCA V3 Web Portal profile.
    4. Appointment of Professional Advisors/ Consultants: Engage qualified and experienced Company Secretaries, Chartered Accountants, Cost and Management Accountants, Legal Advisors, and other professionals as required.
    5. Registered Office and Corporate Particulars: Ensure that the Company’s name, registered office address, registration details, name board in English and the applicable local/vernacular language, and other required particulars are accurate, up to date, and consistently reflected across all official documents, invoices, stationery, and corporate records.
    6. Common Seal of the Company: After incorporation, the Company should decide whether it needs a common seal, subject to the articles (AOA) of the Company. If it maintains one, the Company should control its custody, access, and use.
    7. Post-Incorporation Compliance for Pre-Incorporation Expenses and Contracts: All genuine expenses incurred and contracts entered into before the Company’s registration shall be reviewed and duly regularised subject to the approval of Board of Company as per the Company Law. Where required, such contracts shall be novated in favour of the Company with the consent of the related counter parties and approval of the Board. All such transactions shall be properly documented, authorised, and accounted for in accordance with applicable laws and accounting standards.
    8. Intellectual Property Protection: Identify the Company’s key trademarks, brand assets, domain names, copyrights, and other intellectual property. Maintain clear ownership records and take appropriate steps to register and protect them based on the Company’s business needs. For more detailed information, Please read Startup, MSME Trademark Registration: Checklist for Indian Founders and Role of Intellectual Property in Corporate Brand Protection and Please click here to conduct a Trademark search
    9. Employment and HR Framework: Implement appropriate employment agreements, HR policies, payroll processes and employee records, and ensure compliance with applicable labour and employment laws following the Company’s registration.
    Practical Issues, Key Queries & Solutions on Post-Incorporation Compliance

    Practical Issues on Post-Incorporation Compliance: Common Queries & Solutions-Continue-1

    Q-1. What happens if a company does not file the Declaration of Commencement of Business (INC-20A)?

    Sol. A company cannot legally commence its business or exercise its borrowing powers until it files INC-20A. Its bank account is not automatically frozen or closed, but the company should avoid business transactions, banking activities related to commencing business, and borrowings until the form is filed. The company and its officers may also be liable to penalties under the Companies Act, 2013.

    Q-2: What are the statutory timelines for a newly registered company to receive the subscription money mentioned in the MOA and issue share certificates?

    Sol: The company must receive the subscription money mentioned in the MOA before filing Form INC-20A, which is required to be filed within 180 days of incorporation. Share certificates must be issued within two months of incorporation. Therefore, the subscription money should preferably be received within two months.

    Q-3: What are the annual compliance requirements of a company under the Companies Act, 2013?

    Sol: Under the Companies Act, 2013, every company must complete its annual compliance requirements, including holding the Annual General Meeting (AGM) within the prescribed time, filing the Annual Return within 60 days of the AGM, and filing the Financial Statements within 30 days of the AGM.

    Q-4. When is the first AGM required to be held?

    Sol: Under Section 96 of the Companies Act, 2013, the first AGM of a company, other than an OPC, must be held within 9 months from the end of its first financial year. Subsequent AGMs must generally be held within 6 months from the end of the financial year. For a newly incorporated company, the first financial year commences from the date of its incorporation and ends on 31 March of the following year, subject to the provisions of Section 2(41) of the Companies Act, 2013.

    Practical Issues, Key Queries & Solutions →

    Q-5. What is DIR-3 KYC and when does it apply?

    Sol: DIR-3 KYC is an annual verification of a director’s details with the MCA. It helps the MCA maintain updated information about DIN holders. For more detailed information, please read DIR-3 KYC 2026: New Rules, Due Date & Once-in-Three-Years KYC

    Q-6. Is a promoter’s pre-incorporation contract automatically binding on the company once it is incorporated?

    Sol: No. Not automatically. A company exists only after incorporation, so a contract made by promoters before incorporation does not automatically become binding on the company after it is incorporated.

    Q-7. Can the company just pass a Board resolution saying, “All pre-incorporation contracts are approved”?

    Sol: No, each pre-incorporation contract should be reviewed individually and, where appropriate, formally adopted by the company with the requisite Board approval and communicated to the relevant counterparty, and, where necessary, novated with the relevant counterparty, subject to the provisions of the Specific Relief Act, 1963.

    Practical Issues, Key Queries & Solutions →

    Q-8. Question: Who is liable or responsible for an agreement entered into before the incorporation of a company?

    Sol: Generally, the promoter or person who entered into the contract remains personally liable, even after the company is incorporated.

    Q-9. How should we treat expenses paid by the promoters before the company opened its bank account?

    Sol: The company can record genuine expenses paid by the promoters on its behalf and reimburse them after opening the bank account, subject to Board approval and proper supporting documents.

    Q-10. Is a Common Seal Mandatory for an Indian Company After Incorporation?

    Sol: No. A common seal is not mandatory, unless required under the company’s Articles of Association.

    Authored by Team RYmergZ

    About the Author:

    A Corporate Professional, having the Post Qualification Experience of Fifteen Years Plus, in the areas of Corporate Laws and Governance, Regulatory Reporting, Contract Management, Compliance and Risk Governance.

    Please contact us if you require professional advice. https://rymergz.me/contact-us/
  • Blog - Company Law

    DIR-3 KYC 2026: New Rules, Due Date & Once-in-Three-Years KYC.

    DIR-3 KYC 2026: DIN holders now need to update their KYC details only once every three years instead of every year

    DIR-3 KYC 2026 DIN holders now need to update their KYC details only once every three years instead of every year

    DIR-3 KYC 2026: DIN holders now need to update their KYC details only once every three years instead of every year. The MCA Rules amended on 31st December, 2025 replace annual KYC filing with a simple KYC intimation once every three years. The new KYC Form “DIR-3-KYC-WEB” replaces the earlier “DIR-3 KYC” and “DIR-3 KYC-WEB” forms and provides a simpler process for various KYC purposes.

    The MCA introduced the Companies (Appointment and Qualification of Directors) Amendment Rules, 2025, effective from 31st March 2026, to simplify the DIN KYC process and its related procedures. To maintain an active Director Identification Number (DIN)/Designated Partner Identification Number (DPIN), the Director or Designated Partner must complete the prescribed DIR-3 KYC-Web requirements, comply with the applicable three-year compliance window, and verify the registered mobile number and email address within the prescribed timelines.

    The Companies (Appointment and Qualification of Directors) Amendment Rules, 2025

    https://www.mca.gov.in/bin/dms/getdocument?mds=Vk%252FT5sIBKBare6St1b%252FznQ%253D%253D&type=open,

    Important MCA Clarification on DIN KYC Update for Directors Effective from 31 March 2026 under Notification No. G.S.R. 943(E) dated 31 December 2025:

    https://www.mca.gov.in/bin/dms/getdocument?mds=5wBuXrnw5F5hFYBugmtq1Q%253D%253D&type=open

    DIR-3 KYC-Web Key Applicable Scenarios

    DIR-3 KYC-Web: Key Applicable Scenarios

    Every individual holding a DIN as on 31st March of a financial year must file DIR-3 KYC-Web by 30th June of the next third consecutive financial year, without any fee. If the mobile number, email address, or residential address changes, the DIN holder must file DIR-3-KYC-Web within 30 days of the change, with the applicable fee.

    The Form DIR-3 KYC-Web covers the following scenarios:
    ScenarioPurposeTime LimitGovernment Fee
    Reactivation of DIN  Applicable where the DIN status is “Deactivated due to non-filing of DIR-3-KYC”NA  ₹5000  
    KYC Compliance
    (For Every Three-Year Compliance Window)  
      Applicable, if the DIN status is “Approved”.  30th June of the next third consecutive financial year (*) i.e 30/06/2028 for First KYC WindowNIL    
    Update of Mobile Number/ Email ID/ Permanent and Present Residential AddressApplicable, if the DIN status is “Approved”.   within a period of thirty days of such event of change  ₹500      
    (*) The first three-year compliance window is from 01st April, 2025 to 31st March, 2028, and the “KYC Compliance” function will be enabled on the MCA Portal for the first time after 31st March 2028.
    Practical Issues, Key Queries & Solutions on DIN DIR-3 KYC Compliance

    Practical Issues, Key Queries & Solutions on DIN DIR-3KYC Compliance

    Q-1. What changes were introduced in DIN DIR-3 KYC compliance from 31st March 2026?

    Sol: From 31st March 2026, the revised DIN KYC process requires All DIN holders to complete KYC compliance once every three consecutive financial years instead of every year. The DIN holders must use DIR-3 KYC-Web for the applicable KYC compliance, replacing the earlier DIR-3-KYC and DIR-3-KYC-Web process.

    Q-2. What is the first three-year KYC window, and when will “KYC Compliance” be available on the MCA Portal?

    Sol: The first three-year KYC window is from 1st April 2025 to 31st March 2028. The “KYC Compliance” function will first be available on the MCA Portal after 31st March 2028.

    Q-3. Does the three-year cycle eliminate the requirement to update changed KYC details?

    Sol: No, the three-year cycle applies to the regular KYC compliance requirement. Where the specified personal details change, the DIN holder must update them within 30 days of the change, along with the applicable fee of ₹500.

    Q-4. Is the “KYC Compliance” function applicable to every Deactivated DIN?

    Sol: No, it’s applicability depends on the reason for deactivation and the DIN KYC filing history. In particular, the revised mechanism needs to be distinguished from cases where the DIN was deactivated and the holder had never filed DIR-3-KYC at least once, particularly where the DIN was allotted on or before 31st March 2025.

    Q-5. Will DIN holders with different DIN allotment dates, follow the same KYC Compliance Cycle as per New Rules?

    Sol: Yes, All DIN holders will follow a uniform three-year KYC Compliance cycle, subject to applicable provisions and transitional rules as amended time to time.

    Practical Issues, Key Queries & Solutions on DIN DIR-3 KYC Compliance →

    Q-6. Is DIR-3 KYC-Web applicable to all categories of DIN holders?

    Sol: Yes. DIR-3 KYC-Web applies to DIN holders irrespective of their category or status, including NRI, Foreign Nationals, Independent Directors, Professional Directors, and other Directors, subject to the applicable provisions and transitional requirements.

    Q-7. Does the residential status or category of a Director affect the applicability of DIR-3 KYC-Web?

    Sol: No. The applicability of DIR-3 KYC-Web is determined based on the DIN holder and the applicable KYC requirements, and does not vary merely because the individual is an NRI, Foreign National, Independent Director, Professional Director, or belongs to any other category of Director.

    Q-8. Can an NRI or Foreign Director use a foreign mobile number for DIN DIR-3 KYC-Web?

    Sol: Yes, An NRI or Foreign Director can use a valid foreign mobile number for DIN KYC. An Indian mobile number is not mandatory if the foreign number meets the applicable requirements and can receive the required OTP. The DIN holder can also update the mobile number through DIR-3 KYC-Web when required.

    Q-9. When is Form DIR-3 KYC-Web required to be filed for a DIN allotted during the Financial Year 2025-26?

    Sol: The first filing shall be due from 01st April 2029 to 30th June 2029, and thereafter every third financial year.

    Q-10. What happens if a DIN holder fails to complete DIR-3 KYC, and how can the DIN be regularised?

    Sol: If a DIN holder fails to complete the prescribed DIR-3 KYC within the applicable period, the DIN will be deactivated. To regularise the DIN, the holder must complete the required KYC through the MCA V3 portal and pay the applicable fee or late fee, if any.

    Practical Issues, Key Queries & Solutions on DIN DIR-3 KYC Compliance ■

    Q-11. Where the DIN was allotted on or before 31st March 2025 and the DIR-3 KYC was filed for FY 2025-26, is filing required for FY 2026-27 or FY 2027-28, and when will the next filing be due?

    Sol: Where a Director already filed the Form DIR-3 KYC / DIR-3 KYC-Web for the FY 2025-26, i.e. where DIN allotment date is on or before 31st March 2025, no filing shall be required for FY’s 2026-27 and 2027-28, provided that there is no change in KYC particulars like address, phone number, email id etc. Accordingly, the first filing in such case shall be due from 01st April 2028 to 30th June 2028.

    Q-12. If a DIN is allotted during FY 2025-26 and the Director updates KYC particulars through DIR-3 KYC-Web during FY 2027-28, when will the next KYC compliance filing be due?

    Sol: Where a DIN is allotted on 1st March, 2026 [FY 2025-26] and the Director updates the phone number, email id, or address in FY 2027-28 by filing DIR-3 KYC Web, the three-year compliance cycle shall be reckoned from the FY 2025-26 in which the DIN is allotted. Accordingly, the next DIR-3 KYC Web for KYC compliance shall be due from 1st April, 2029 to 30th June, 2029. Any update made in FY 2027-28, will not impact the cycle for KYC update compliance mechanism.

    Authored by Team RYmergZ

    About the Author:

    A Corporate Professional, having the Post Qualification Experience of Fifteen Years Plus, in the areas of Corporate Laws and Governance, Regulatory Reporting, Contract Management, Compliance and Risk Governance.

    Please contact us if you require professional advice. https://rymergz.me/contact-us/
  • Blog - Company Law

    Director Identification Number (DIN) and DPIN for LLP-2026

    Director Identification Number (DIN) for Companies and DPIN for LLPs: Legal Framework, Eligibility, Applicability, Application, Allotment and Regulatory Requirements for Individuals, NRIs and Foreign Nationals

    Director Identification Number (DIN) or DPIN is a unique number allotted by Central Government, under the Companies Act, 2013,

    Director Identification Number (DIN) or DPIN is a unique number allotted by Central Government, under the Companies Act, 2013, to identify company directors within the Indian Corporate Governance Framework i.e Company and LLP. The primary purpose of DIN is to uniquely identify company directors for the legal and administrative requirements of a company. The DIN under the Companies Act, 2013 also serves as the Designated Partnership Identification Number (DPIN) under the Limited Liability Partnership Act, 2008.

    Applicability: the DIN is applicable only to Directors of Companies and Designated Partners of LLPs. No person can be appointed as a Director in a Company or as a Designated Partner in an LLP without a DIN. The term ‘company’ includes all types of companies, such as private companies, public companies, One Person Companies (OPCs), Producer Companies, etc.

    What is the Procedure for Applying and Allotment of Director Identification Number (DIN)

    What is the Procedure for Applying for Allotment of DIN / DPIN:?

    The Ministry of Corporate Affairs (MCA) allots DIN based on the PAN for Indian Nationals and on the passport and other prescribed identification and supporting documents for Foreign Nationals. The PAN serves as the primary identification reference for DIN allotment and verification for Indian Nationals. As per the Companies Act, 2013, the procedure for applying for allotment of a DIN depends on whether the individual is proposed to be appointed as a director in a new company or an existing company.

    Procedure for Allotment of Director Identification Number (DIN) / DPIN:

    1. For a Director of a New Company [through → SPICe+ (INC-32)] and For a Designated Partner of a New LLP [through → Form FiLLiP]

    The Director Identification Number (DIN) application is made through SPICe+ (INC-32) as part of the company incorporation process. DIN can generally be allotted to up to three proposed directors through SPICe+. The DPIN application is made through Form FiLLiP as part of the LLP incorporation process, respectively.

    2. For a Director of an Existing Company (through an Application Form DIR-3)

    The proposed director must apply through Form DIR-3 before appointment. The procedure is as below:

    1. Obtain the required Digital Signature Certificate (DSC).
    2. Prepare Form DIR-3 on the MCA V3 Portal (www.mca.gov.in).
    3. Enter the applicant’s particulars, including PAN/passport details, name, father’s name, date of birth, nationality and address.
    4. Attach the prescribed supporting documents, including photograph, proof of identity and proof of residence.
    5. Attach the Board Resolution proposing the appointment as director (optional).
    6. Ensure the form is digitally signed by the applicant and digitally verified by the appropriate authorised person of the company/ LLP i.e Existing Director of Company/ Designated Partner of LLP.
    7. Submit the form electronically on the MCA portal and pay prescribed fee of INR. 500/-.
    8. MCA processes the application and, if approved, allots the DIN.
    Change in DIN Particulars and Maintenance of DIN Active Status and Cancelation/ Surrender of DIN

    Change in DIN Particulars and Maintenance of DIN Active Status

    The Director of a Company or Designated Partner of an LLP must file Form DIR-6 with the MCA/ROC, as applicable, along with the prescribed supporting documents, within 30 days of any change in DIN particulars, in accordance with the applicable DIN Rules. No Government fee is applicable for filing Form DIR-6. To maintain the active status of the DIN, the Director or Designated Partner must comply with the prescribed DIR-3 KYC-Web requirements, including the applicable three-year compliance window under the latest rules notified on 31st December, 2025, https://www.mca.gov.in/bin/dms/getdocument?mds=Vk%252FT5sIBKBare6St1b%252FznQ%253D%253D&type=open, verify the registered mobile number and email address, and complete all required compliance’s within the prescribed timelines. For a comprehensive guide to the updated DIR-3 KYC Web requirements, please refer to our detailed article, DIR-3 KYC 2026: New Rules and Compliance Requirements.

    Cancelation/ Surrender of DIN:

    The DIN holder can surrender or cancel the DIN by filing Form DIR-5 with the MCA/ROC, along with the prescribed supporting documents, upon verification and satisfaction of the requirements as per rules, the MCA approves the application and deactivates the Director Identification Number (DIN).

    Important MCA Update for Directors for DIN KYC wef 31st March 2026 as per the vide Notification No. G.S.R. 943(E) dated 31st December, 2025:

    https://www.mca.gov.in/bin/dms/getdocument? mds=5wBuXrnw5F5hFYBugmtq1Q%253D%253D&type=open

    DIN-Related Forms: Purpose, Filing Requirements, Time Limits and Government Fees
    DIN-Related Forms: Purpose, Filing Requirements, Time Limits and Government Fees:Top of Form
    Form DetailsPurposeTime LimitGovernment Fee
    DIR-3Application for Allotment of DINBefore Appointment₹500
    DIR-3 KYC Web    
    For a comprehensive guide to the updated DIR-3 KYC Web requirements, please refer to our detailed article, DIR-3 KYC 2026: New Rules and Compliance Requirements.        
      DIN holders to “KYC Compliance/ KYC Update/ Reactivation”   Note: The purpose “KYC Compliance” will be enabled for the first time after 31 March 2028  Annual Based intimation: On or before 30th June of the immediately following every third consecutive financial year   Event Based: within a period of thirty days of such event of change  KYC Compliance: NIL   Reactivation of DIN: ₹5000   KYC Update: ₹500      
    DIR-5  Application for Cancelation/ surrender of DINNA  ₹1000
    DIR-6Intimation of change in DIN particularswithin a period of thirty days of such changeNil
    DIR-9    Filing the report by the company to ROC (MCA) about disqualification of a directorNA    As per Companies Fees Rules    
    DIR-10    Filing the application to Regional Director (MCA) to remove disqualification of directorsNA    As per Companies Fees Rules    
    DIR-11  Filing application for notice of resignation of a director to the Registrar (MCA)Event of Resignation    As per Companies Fees Rules  
    DIR-12    Particulars of appointment/ Changes of directors/ KMP by Company to the Registrar (MCA)30 Days for normal companies (60 days for IFSC company  As per Companies Fees Rules  
    DIR-3CIntimation of DIN by the company to the Registrar/ ROC.15 days of receiving the intimation from the DirectorAs per Companies Fees Rules
    Key Legal Considerations and Document Verification for DIN Application
    Key Legal Considerations and Document Verification for DIN Application:
    1. One DIN per Individual: An individual can hold only one Director Identification Number (DIN). A fresh DIN should not be applied for if a DIN has already been allotted/ deactivated.
    2. PAN-Based Verification for Indian Nationals: For Indian nationals, the DIN application is linked to PAN-based identification and verification. The particulars entered in the application should match the PAN records, in all respects i.e name, date of birth, surname, father’s name, etc.
    3. Passport-Based Verification for Foreign Nationals: For foreign nationals, passport details are used for identification where PAN is not applicable. The passport should be valid and the particulars entered in the application should match the passport.
    4. Proof of Identity and Address: The prescribed identity and residential-address documents must be attached and should be valid, legible and properly authenticated wherever required.
    5. Certification and Digital Signatures: The DIN application must be digitally signed and verified by the persons required under the applicable MCA rules and form requirements.
    6. Consistency Across Documents: Any mismatch in name, surname, date of birth, father’s name, address or other identification particulars may result in resubmission, rejection or delay.
    7. False or Misleading Information: Providing incorrect, incomplete or misleading information in the DIN application can have legal consequences under the Companies Act, 2013 and the Bharatiya Nyaya Sanhita, 2023 (BNS).
    8. Apostille is not required for NRIs and OCI Cardholders who are present in India, in respect of documents issued by the Indian Government.
    9. OCI Cardholders who hold foreign citizenship and a foreign passport must obtain an apostille for documents issued by the relevant foreign government. 
    10. Documents for Foreign Nationals: Where documents are issued outside India, additional requirements relating to notarisation, apostille/attestation and translation may apply, depending on the document and applicable MCA requirements as the Companies (Appointment and Qualifications of Directors) Rules, 2014 (as amended time to time).
    11. Verification Before Filing: Before submitting the application, verify the applicant’s existing DIN status, PAN/passport particulars, supporting documents, digital signatures and prescribed attachments to minimise rejection or resubmission.
    Practical Issues, Key Queries & Solutions on Director Identification Number (DIN)
    Practical Issues, Key Queries & Solutions on Director Identification Number (DIN):

    Q-1: Can a person hold more than one DIN or DPIN?
    Sol: No. A person should have only one DIN for Life-time. If multiple DINs have been inadvertently allotted, the duplicate DIN(s) should be surrendered through the prescribed MCA (Form DIR-5) process.

    Q-2: Can the same Director Identification Number (DIN) be used for both a Company and an LLP?
    Sol: Yes. A valid DIN can serve as the identification number of an individual acting as a director of a company and/or designated partner of an LLP.

    Q-3: Does resignation from all companies automatically deactivate the DIN?
    Sol: No. Resignation or cessation as a director does not, by itself, cancel or deactivate the DIN. The DIN is an Identification Number to be a Director in a Company or as a Designated Partner in an LLP, and it serves as fundamental requirement for the Directorship.  

    Q-4:Can a DIN deactivated for non-filing of DIR-3-KYC be restored?
    Sol: Yes, by filing of the Form DIR-3-KYC-Web as applicable under the DIN Rules.

    Q-5:Can a person surrender a Director Identification Number (DIN) merely because the person is currently not a director? Sol: No, this is a purely individual strategic needs of the person who holds the DIN.

    Q-6:Can an NRI or foreign national obtain a DIN to become a Director in an Indian Company?
    Sol: Yes, An NRI or foreign national must obtain a DIN and become a director of an Indian company, For a foreign national, the passport serves as the fundamental identity document.

    Practical Issues, Key Queries & Solutions—Continuation:

    Q-7:Can a foreign national/ NRI provide a foreign residential address while applying for DIN? Sol: Yes, A foreign national/ NRI residing outside India can provide the actual overseas residential address as the residential address for DIN/KYC purposes. The address should be supported by an acceptable address-proof documents as per MCA DIN Rules. Where documents are not in English, an appropriate English translation may also be required. Foreign documents may require notarisation and apostille, depending on the applicable requirements and country of issuance.

    Q-8:Can a foreign national/ NRI complete DIN KYC using a foreign mobile number and foreign address? Sol: Yes, subject to the MCA’s prescribed KYC validation requirements, Foreign/ NRI directors should maintain their registered email/mobile details and overseas residential address accurately in MCA records.

    Q-9: Is an NRI automatically treated as a “foreign national” for DIN purposes? Sol: No, This is an important practical distinction. An NRI is generally an Indian citizen residing outside India, whereas a foreign national is a citizen of another country. Therefore, an NRI should not be treated as a foreign national merely because the person has an overseas residential address.

    Authored by Team RYmergZ

    About the Author:

    A Corporate Professional, having the Post Qualification Experience of Fifteen Years Plus, in the areas of Corporate Laws and Governance, Regulatory Reporting, Contract Management, Compliance and Risk Governance.

    Please contact us if you require professional advice. https://rymergz.me/contact-us/
  • Blog - Company Law

    “One Person Company (OPC)”: Its Benefits and Features.

    What is One Person Company OPC

    “One Person Company (OPC)”: Its benefits, features and as a type of Private Limited Company under the Indian Corporate System.

    A One Person Company (OPC) is a version of mixed business structure that combines the limited liability protection of a Private Limited Company with the features of a sole proprietorship under the Companies Act, 2013.

    One Person Company facilitates a single entrepreneur to run the company on his/ her own. OPC represents a type of the private limited company under the Companies Act, 2013

    OPC Name Examples : The word “OPC” shall be inserted as follows as per the company name regulations.

    ABC Software (OPC) Private Limited

    XYZ Exports (OPC) Private Limited

    one person company OPC registration and Basics of Company Registration including One Person Company

    Basics of Company Registration including One Person Company

    The Ministry of Corporate Affairs, is the apex regulator for registration and regulation of companies in India, as governed under the Companies Act, 2013.https://www.mca.gov.in/content/mca/global/en/home.html

    The Company is an artificial juristic person with legal distinct identity from its Shareholder, Directors and Other Key Managerial Personal as defined under the Companies Act, 2013.The Company is a Separate Legal Entity in the eyes of law and society

    Registration procedure of OPC and Core concepts of OPC, how to register one person company in India

    Strategic Legal Considerations in the matter of the One Person Company Registration in India:

    1. OPC is a Private Limited Company with one sole member who can also act as Director.

    2. The OPC can have more than One Director with maximum limit of Fifteen.

    3. The member of OPC, shall nominate a person as his/her Nominee with prior written consent, who shall become the member of that OPC, in the event of the death of member or incapacity to contract, respectively.

    4. A “minor” cannot become a member or nominee of the OPC or hold shares with beneficial interest.

    5. A person shall not be a member or nominee in more than one OPC at any point of time.

    6. A single person can act as Member in One OPC and as Nominee in other One Person Company. If a nominee place triggers and said person becomes a member in two OPCs, then within a period of 180 days, he/she should choose any one OPC as a member and intimate the same to the MCA.

    7. An OPC cannot carry Non-Banking Financial Investment (NBFC) activities, including investment in securities of any Company and LLP.

    8. The member or shareholder of an OPC can be an Indian resident individual or non-resident Indian subjected to his/her stay in India for a period of not less than 120 (one hundred and twenty days) during the immediately preceding financial year. Hence, the Company Law allows NRI to register an OPC in India.

    9. Company Law prohibits a Foreign National from forming an OPC in India

    10. An OPC can convert into a private or public company but cannot convert into a “Section 8 company,” while a private company may convert into an OPC.

    Features and Benefits of one person company

    The Benefits and features of One Person Company (OPC) for Indian Entrepreneurs and Startup Founders:

    • A feature of an OPC is forming a separate legal protection between personal and corporate wealth/Assets. Shareholder/ Member personal assets are legally inaccessible to the business creditors, and liability is strictly limited to the unpaid value of their subscribed share capital.
    • The mandatory clause of an appointment of nominee ensures an immediate transfer of ownership without stumbling operations and also ensures perpetuity.
    • In case of death of member, the One Person Company Contracts or agreements remains unaffected due to the Transmission of shares to nominee as per the Companies Act, 2013.
    • The One Person Company can hold all types of tangible properties, like land, buildings, etc., and intangible properties like intellectual property (IP), know-how, Trademarks, Patents and other forms of Capital in its own name.
    • OPCs are legally relieved from convening General Meetings i.e., Annual General meeting or Extraordinary General Meetings, as per the Company Law, being operated by a Single Member.
    • OPCs are legally also relieved from convening mandatory number of Board Meetings under the Companies Act, 2013, subjected to Minimum of Two Board Meetings.
    • An OPC can, at its convenience/ requirements, voluntarily convert to a Private Limited Company and can preserve its past track record, GST/ PAN history, Company Bank accounts, properties and other contractual rights and obligations.

    Special Advantages for Tech-startups, Technocrat Projects

    Special Advantages for Tech-startups, Technocrat Projects, as OPC has enabled to get registrations under the MSME/ Udyam, Startup India Schemes, Standup India Schemes, holding of registrations of Import Export Code (IEC), FSSAI, APEDA, Spices Board, Rubber Board, Coir Board etc               

    what is meant by one person company , what one person company, how many members can be there in one person company

    One Person Company (OPC) Frequently Asked Questions (FAQs):

    Q-1: Is the foreign citizen and national but a person of Indian origin eligible to register an OPC in India?

    No, Persons of Indian Origin (PIO) or Overseas Citizens of India/ OCI Card Holders, who have taken up foreign citizenship and passports cannot form an OPC in India.

    Q-2: Can a corporate body eligible to register an OPC?

    No. According to the Companies Act, 2013, Only natural persons are eligible to register the OPC.

    Q-3: Is there any minimum authorised and paid-up capital requirement for starting a OPC?

    No. The Companies Act, 2013 does not mandate capital requirement

    Q-4. Can an OPC invest by purchasing or subscribing equity shares in another Private Limited Company?

    No. An OPC cannot allowed to invest/ purchase shares/ ownership rights in any Company/ LLP/ Body Corporate.

    Q-5. Can an OPC accept Foreign Funding?

    No, FEMA Regulations prohibit an OPC from accepting foreign funding/FDI/ECB.

    FAQ Continuity-1.

    Q-6. Can an OPC give secured and unsecured loans to other OPC’s/ Companies?

    Yes, It can lend money to another OPC/ body corporate out of profits generated from its business operations, subject to the provisions of the Companies Act, 2013 as related to the inter corporate loans

    Q-7. What happens to the OPC in the event that the only member is officially declared bankrupt under the Insolvency Laws?

    The member loses his ability to enter into contracts if a court finds them to be legally insolvent. Eventually, the Nominee can become the Member of the OPC, subject to the Transfer of the Ownership of the Shares, subject to the provisions of the Companies Act, 2013.  

    Q-8 Is apostillation of all Documents as related to Identification of an Non-Resident Indian (NRI) is required to form an One Person Company (OPC) in India?

    No, in case of travel to India to register a OPC. Apostillation will be application where he/ she resides the country which is a part of Hague Convention.

    Q-9. When is an attestation by the Indian Embassy and Consulate, required?

     Applicable, where an NRI resides in Non-Hague Convention Countries (e.g., UAE, Saudi Arabia, Singapore).

    Authored by Team RYmergZ

    About the Author:

    A Corporate Professional, having the Post Qualification Experience of Fifteen Years Plus, in the areas of Corporate Laws and Governance, Regulatory Reporting, Contract Management, Compliance and Risk Governance.

    Please contact us if you require professional advice. https://rymergz.me/contact-us/